I treat auto insurance as a set of decisions, not a bundle handed over at one fixed price. Every policy I write begins with what gets driven, where it travels, and what would genuinely need replacing if a claim ever landed.
That order matters. I size liability limits to real assets and income. Comprehensive and collision stay on the policy only while the vehicle value still supports the math. Extras earn their place by solving a clear problem rather than padding a quote.
The result is a premium that reflects real choices, line by line, with the reasoning I attach at every step. Nothing hidden in a preset, nothing carried forward simply because last year carried it.
I size coverage in a set order, so every layer on the policy can be traced back to a clear reason rather than a preset bundle.
The driver, the vehicle, the mileage, and where it parks set the starting point for every sizing decision.
Real assets and income shape liability limits, while current value decides whether collision and comprehensive stay.
Each layer I list arrives with its limit and the reasoning attached, so the premium reads line by line, not as one figure.
A quick check I run each renewal keeps coverage aligned as mileage, vehicle value, and the assets behind it shift.
Auto insurance is one product priced in distinct layers. I separate the core three so each one can be sized, kept, or trimmed on its own. The premium reflects the choices, line by line.
Limits sized to actual assets and income, not the state minimum that leaves a gap the day a claim lands.
Explore Liability
Kept on the policy only while the vehicle's market value still supports the premium and deductible math.
Explore Collision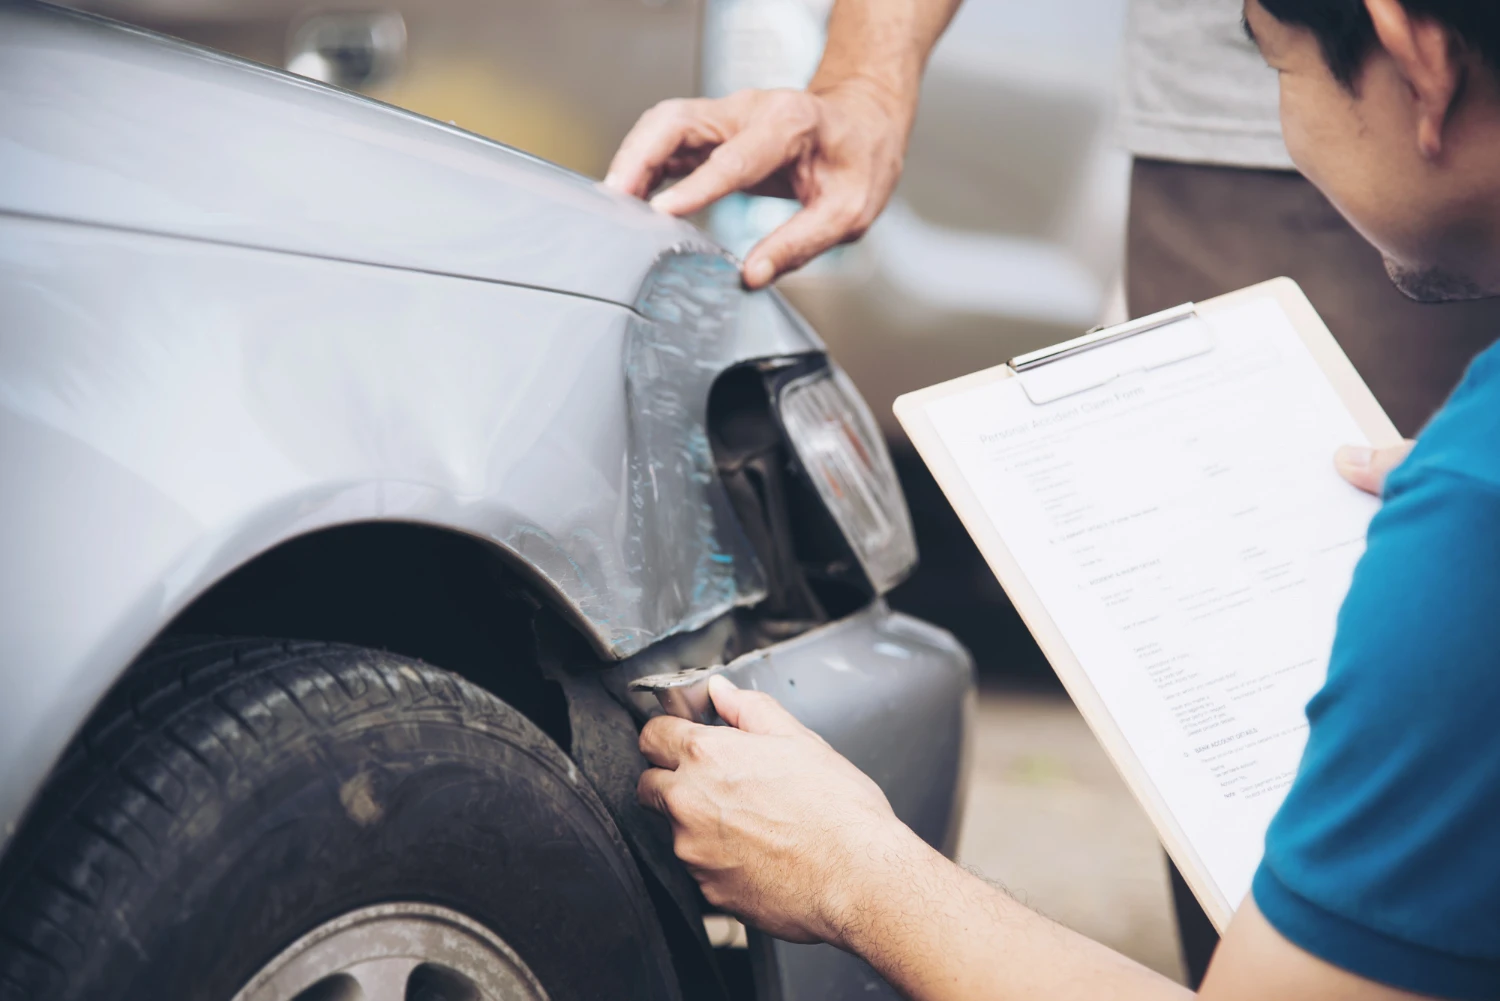
Theft, weather, glass, and animal strikes priced against where the car parks, not a national average.
Explore Comp
Share the basics on the driver and vehicle. I send back an itemized quote, layer by layer, with the reasoning attached and no surprise renewal upsell.
Get a Quote