I read auto coverage line by line, never as one lump price. Every layer carries its own purpose, its own limit, and its own threshold for staying on the policy or coming off it.
The sections below set out how I size each layer and when it earns its place. I keep the reasoning attached to the number, so a quote can be understood at a glance rather than accepted on trust.
Three core layers carry most auto policies. Here is what each one protects, how I size it, and the signals that decide whether it stays.
The foundation of any auto policy. It answers for injury and property damage caused to others, which is where the largest claims tend to land.
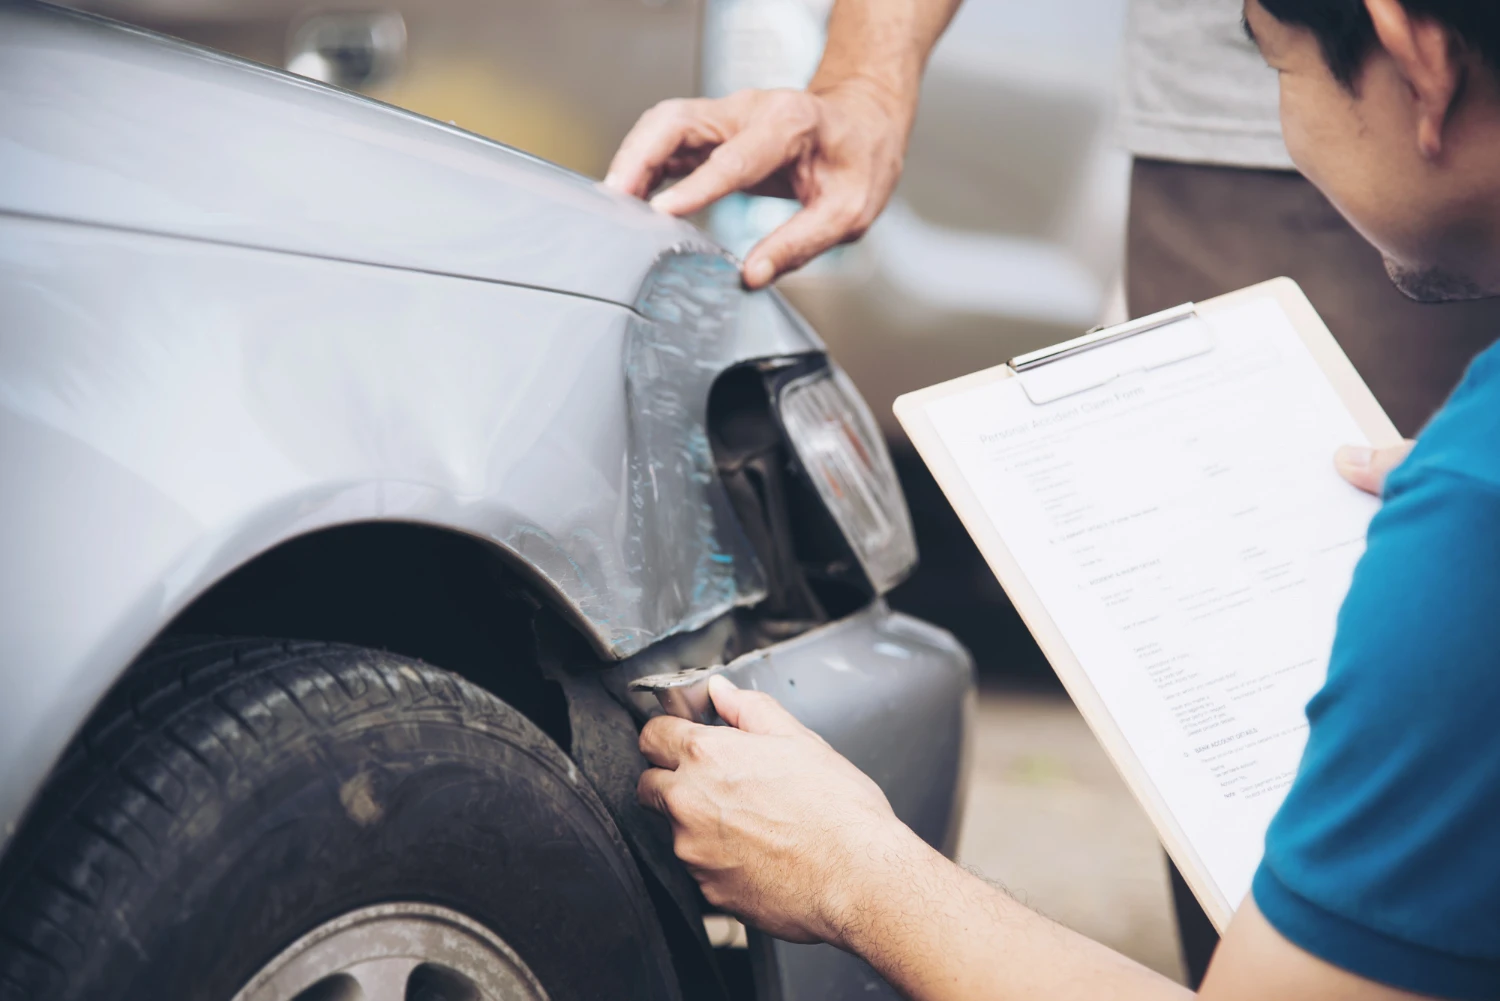
Covers damage to the insured vehicle from a crash, regardless of fault. It stays valuable only while the vehicle is worth enough to justify the cost.
Handles loss outside a collision: theft, weather, glass, fire, and animal strikes. Its value depends heavily on where the vehicle lives and parks.
I size coverage in a set order, so every layer on the policy can be traced back to a clear reason rather than a preset bundle.
The driver, the vehicle, the mileage, and where it parks set the starting point for every sizing decision.
Real assets and income shape liability limits, while current value decides whether collision and comprehensive stay.
Each layer I list arrives with its limit and the reasoning attached, so the premium reads line by line, not as one figure.
A quick check I run each renewal keeps coverage aligned as mileage, vehicle value, and the assets behind it shift.
Share the basics on the driver and vehicle. I send back an itemized quote, layer by layer, with the reasoning attached and no surprise renewal upsell.
Get a Quote